Latest News Feed
- Monthly subscription value of $1.83 million as of October 31, 2026, approximately $22.0 million on an annualized basis
- 12,532 active U.S. subscriptions as of October 31, 2026
- October U.S. e-commerce total sales of $1.67 million, of which approximately $1.02 million, or 61%, was attributable to subscriptions
- Approximately 19,100 orders in October from approximately 234,500 online store sessions
- Continued momentum in November, with U.S. e-commerce sales continuing to grow significantly
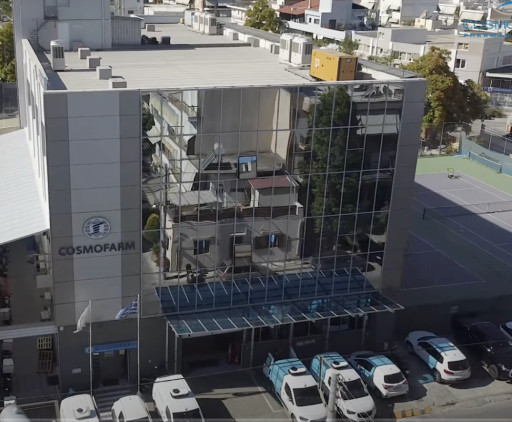
- New order-processing line: automated handling cell and roller conveyor now being commissioned at CosmoFarm's distribution center in Peristeri, Athens, designed to move more orders through the facility in less time
- New vehicle-loading lanes: multiple rows of roller flow lanes designed to significantly reduce the time needed to load each delivery vehicle
- Earlier dispatch: faster processing and loading are expected to get vehicles on the road sooner, supporting earlier pharmacy deliveries and capacity for additional routes
- Acquisition pipeline: CosmoFarm has an active letter of intent to acquire a network with approximately €10 million (approximately $11.3 million) in annual gross revenue, which, if completed, would be its largest acquisition to date
- Ongoing automation program: the new infrastructure is part of CosmoFarm's multi-year program in robotics, automation and artificial intelligence
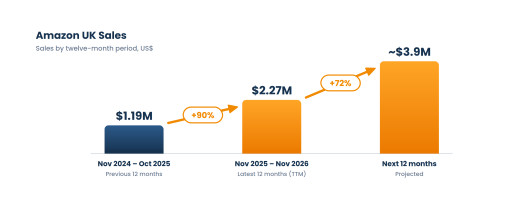
- Amazon UK sales up 90%: $2.27 million in TTM sales for the twelve months to November 2, 2026, up from approximately $1.19 million in the prior twelve months
- 23% net margin on Amazon UK: the Amazon UK channel generated $525,000 in net profit after all direct channel costs, including Amazon fees, cost of goods, shipping, advertising and VAT
- 116,978 units sold on Amazon UK: an average of approximately 320 units per day
- Record performance: July through October 2026 were the four strongest months to date on Amazon UK, each with sales above $215,000
- Efficient growth: advertising costs of only 2.4% of Amazon UK sales, with refunds below 1%
- 72% growth expected: the Company expects Amazon UK sales of approximately $3.9 million over the next twelve months, an average of approximately $325,000 per month
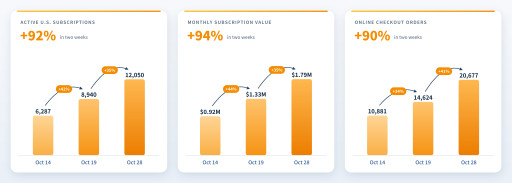
- Active subscriptions up 92%: 12,050 active U.S. subscriptions as of October 28, 2026, up from 6,287 on October 14, 2026
- Monthly subscription value up 94%: $1,787,585 at standard renewal pricing as of October 28, 2026, up from $919,945 on October 14, 2026
- Order volume up 90%: 20,677 online checkout orders tracked as of October 28, 2026, up from 10,881 on October 14, 2026
- Recurring growth: subscriptions renew on a recurring basis, building a growing base of repeat customers
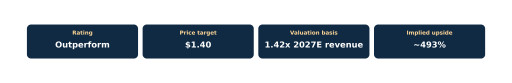
- Rating and price target: Outperform rating with a $1.40 price target
- Implied upside: approximately 493% above the $0.236 closing price on Tuesday, October 27, 2026
- Valuation basis: 1.42 times Noble's 2027 revenue estimate, a discount to the 1.5 times peer average
- Record fourth quarter: Noble forecasts fourth-quarter 2026 revenue of $35.7 million and adjusted EBITDA of $6.4 million
- Accelerating revenue growth: Noble forecasts revenue of $90.0 million in 2026, up approximately 38%, rising 46% to $131.2 million in 2027
- Positive adjusted EBITDA in 2026: Noble forecasts adjusted EBITDA of $3.9 million
- Positive free cash flow in 2027: Noble forecasts free cash flow of $10.0 million
- Now live in Oceania: e-commerce subscription business operating across Australia, New Zealand and the broader Oceania region, with sales already underway
- Attractive markets: together, Australia and New Zealand represent multibillion-dollar, well-established health and wellness markets with strong consumer demand and high e-commerce adoption
- Scalable platform: powered by the same platform behind the Company's growth in the United States
- Global ambitions: Oceania marks the next step in bringing the Company's subscription model to additional international markets
Key Highlights
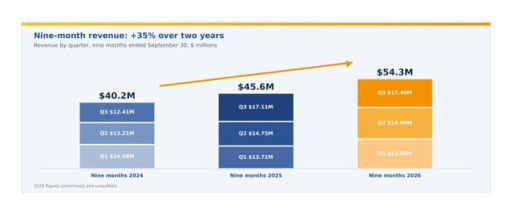
- Record revenue: preliminary nine-month 2026 revenue of approximately $54.3 million, up 19%, with every quarter of 2026 setting a record
- 2026 outlook reaffirmed: full-year revenue expected to surpass $90 million, up approximately 38%, the largest single-year revenue increase in the Company's history
- Record fourth quarter expected: revenue of approximately $35.7 million or more, up approximately 81% from the fourth quarter of 2025
- Multiple engines of growth: pharmaceutical contract manufacturing and distribution, proprietary brands and U.S. e-commerce all expected to contribute
- U.S. e-commerce scaling rapidly: 8,940 active U.S. subscriptions as of October 19, 2026, up 42% in five days, with approximately $15 million in revenue and $10.5 million in gross profit expected in the fourth quarter
- Record CMO pipeline: more than 32.7 million units at Cana Laboratories, up sixfold since mid-2024
- Record distribution volumes: CosmoFarm serving more than 1,500 pharmacies, with revenue up approximately 4.3 times under Cosmos Health ownership
- Global brand expansion: proprietary brands sold in more than 40 countries, with particular momentum in Europe and the Gulf
- Diversified balance sheet: approximately $20 million in non-core assets, including real estate and digital assets, and total liabilities down 13.3% in the first half of 2026
- Share repurchases: more than 5.1 million shares repurchased for approximately $1.1 million
- R&D in weight management: advancing CCX0722, a hydrogel-based weight-management device with patent applications in four major markets
- Path to 2029: <
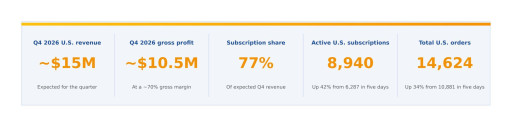
● Q4 2026 U.S. revenue: approximately $15 million expected, based on the Company's current growth trajectory
● Q4 2026 gross profit: approximately $10.5 million expected, at an approximately 70% gross margin
● Subscription revenue: approximately $11.5 million expected, from approximately $8.2 million in first orders and approximately $3.3 million in renewals
● Order volume: 14,624 online checkout orders tracked as of October 19, 2026, up 34% from the 10,881 announced on October 14, 2026
● Subscription growth: 8,940 active subscriptions as of October 19, 2026, up 42% from the 6,287 announced on October 14, 2026, with more than 40,000 expected by year-end
● Monthly subscription value: $1,325,338 at standard renewal pricing as of October 19, 2026, up 44% from $919,945 announced on October 14, 2026
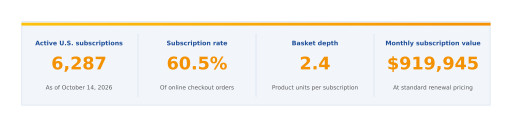
● 6,287 active U.S. subscriptions as of October 14, 2026, the vast majority added since mid-September as the Company accelerates investment in its U.S. platform
● 60.5% of U.S. online checkout orders included a subscription, rising to more than 75% in recent days as adoption accelerates
● $919,945 monthly subscription value at standard renewal pricing as of October 14, 2026
● 2.4 product units per subscription on average, with 14,793 units across 12,408 active subscription lines
● 10,881 U.S. online checkout orders tracked by the Company's subscription management platform
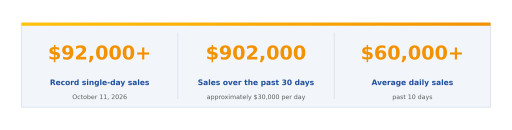
- Record day: U.S. direct-to-consumer sales exceeded $92,000 on October 11, 2026, the highest single day to date
- $902,000 in 30 days: approximately $30,000 in average daily sales over the trailing 30-day period
- Accelerating: average daily sales of more than $60,000 over the past 10 days, double the 30-day average
- Approaching U.S. target: the 10-day pace, if sustained, corresponds to approximately $21.9 million annualized, nearing the over $23 million in annual U.S. revenue the Company previously projected within 12 to 18 months
- Platform to scale: the Company is evaluating extending the model to additional brands and markets
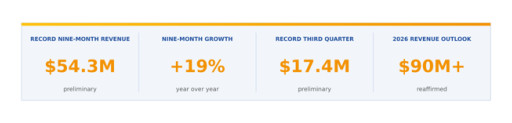
- Record nine-month revenue of approximately $54.3 million - up 19%, or $8.7 million, from $45.6 million in the same period of 2025
- Nine-month 2026 revenue nearly matches the whole of 2024 - when full-year revenue was $54.4 million - and represents 83% of record full-year 2025 revenue of $65.3 million
- Record third-quarter revenue of approximately $17.4 million - exceeding the previous Q3 record of $17.1 million set in 2025, and up 40% on Q3 2024
- Every quarter of 2026 has set a record for its period - Q1, Q2 and Q3 each exceeded the highest revenue previously reported for that quarter
- Growth across all core segments - contract manufacturing, pharmaceutical distribution and proprietary brands, with accelerating sales momentum in the United States
- 2026 revenue outlook reaffirmed - the Company continues to expect full-year revenue to surpass $90 million, with the fourth quarter expected to be the strongest in its history
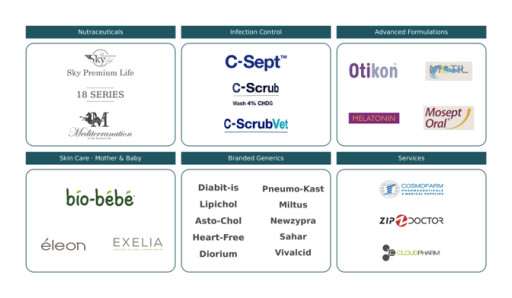
- More than 15 proprietary brands and product lines, plus 10 branded generics - across nutraceuticals, infection control, advanced formulations, skin care and mother & baby, and branded generics
- Proprietary brands sold in more than 40 countries - across Europe, the Middle East, North America and Asia, through pharmacies, hospitals, retail chains and e-commerce
- Addressable markets of approximately $946 billion - the six product categories and two service markets in which the Company competes are estimated by third-party research at approximately $946 billion in 2025, projected to reach approximately $1.76 trillion by 2033
- Infection control gaining hospital and retail traction - C-Scrub listed at Tesco and Superdrug and tested under EN 12791 for surgical hand disinfection; C-Sept PRO adopted across leading Greek hospital groups; C-ScrubVet launched into animal health
- Gross margins of over 70% expected across key brands - including Sky Premium Life, the 18 Series, C-Scrub and C-Sept
- Manufactured at GMP-certified facilities on two continents - principally at Cana Laboratories' EU GMP-licensed, EMA-certified facility in Athens, and at GMP-certified, FDA-registered facilities in the United States
- Supported by integrated services - contract manufacturing at Cana Laboratories, pharmaceutical distribution in Greece and the United Kingdom, ZipDoctor telehealth in the United States, and AI-enabled research and development
- A platform for future brands - registrations, distribution partners, retail and hospital listings and manufacturing capacity already in place are expected to support further launches into existing markets at lower cost and in less time
- Record Q2 2026 revenue of over $15 million, an annualized run-rate of over $60 million, at wholly owned subsidiary CosmoFarm
- Revenue up 4.3x under Cosmos Health ownership - from ~$14 million in fiscal 2017, the last full year before acquisition, to an annualized run-rate of over $60 million; ~330% growth at a CAGR of approximately 18%
- Successive record revenue years in 2023, 2024 and 2025, with 2026 expected to continue the trend, based on distribution volumes and performance to date
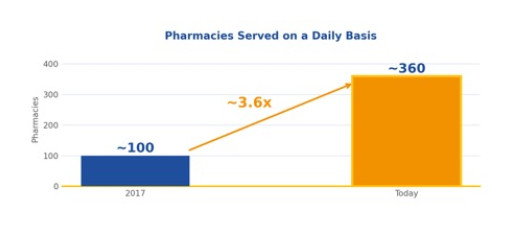
- Pharmacies served daily up 3.6x, from ~100 in 2017 to ~360 today, within a total network of more than 1,500 pharmacies
- Operating leverage from enhanced route density and optimized order execution - during 2025, revenue per customer up 12%, profitability per customer up 14% and the active customer base up 20%
- Robotics, automation and AI-enabled systems across procurement, inventory and order execution, with capacity that could support a further $40 million or more in annual revenue, which would provide infrastructure for annualized revenue above $100 million
- Instrumental to the Company's 2029 guidance of $200.6 million in revenue, $71.2 million in gross profit, $44.2 million in adjusted EBITDA and $31.0 million in net income
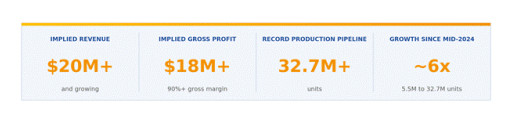
- Contract manufacturing pipeline surpasses $20 million in implied revenue at wholly owned subsidiary Cana Laboratories, representing over $18 million in implied gross profit across the life of agreements
- Gross margins of over 90% - among the highest-margin revenue streams in the Company, with raw materials largely supplied by clients
- Record production pipeline of more than 32.7 million units, up approximately sixfold since mid-2024 and close to threefold since the start of this year, with 7.7 million units added in September alone
- Diversified across 11 therapeutic categories, reducing dependence on any single product or partner, under multi-year agreements averaging approximately four years, with certain contracts extending up to ten years
- Ongoing investment program underway to take Cana to the next level of capacity and capability, as the division scales toward its target of over $10 million in recurring annual gross profit
- Supports the Company's 2029 guidance targets of $200.6 million in revenue and $71.2 million in gross profit, with high-margin contract manufacturing a key driver of the planned margin expansion
- 7.7 million contracted units added in under two weeks - Cana Laboratories' orderbook has grown from over 12 million units earlier this year to more than 32.7 million today
- Secured orders for 1.04 million units annually - 5.2 million over five years - under new agreements with Target Pharma
- Coverage extended to 11 therapeutic categories with the addition of cardiovascular and anti-infective, up from nine in June 2026
- Agreements extending up to ten years provide long-term visibility on production volumes and associated cash flows
- Division targeted to generate over $10 million in recurring annual profit at full capacity
- Prime Ledger engaged to structure an asset-specific, non-dilutive tokenized financing for CCX0722 - backed by intellectual property, with no issuance of Cosmos Health common stock
- Positions Cosmos Health among the earliest NASDAQ-listed healthcare companies pursuing tokenized IP-backed assets.
- CCX0722 is an ingestible, hydrogel-based medical device in development for weight management, using a mechanical mechanism with no systemic absorption
- Intellectual property owned outright, with patent applications advanced into the United States, Europe, Australia and Canada
- Addresses a global weight management market projected to reach $562.2 billion by 2033 (14.2% CAGR) - set against a broader tokenized real-world-asset market projected to reach $18.9 trillion by 2033
- 500,000 contracted units of ROSARTIA annually / 2.5 million over five years through a new long-term agreement at wholly owned subsidiary Cana Laboratories
- Expands Cosmos Health's manufacturing presence in cardiovascular pharmaceuticals, adding production of statin-based lipid-lowering therapies to Cana's growing contract manufacturing portfolio
- Cumulative contract manufacturing orderbook increases to more than 27.5 million units, up from over 25 million units reported in June 2026
- Further strengthens recurring cash flow visibility and expands Cana's long-term manufacturing relationships with established pharmaceutical companies
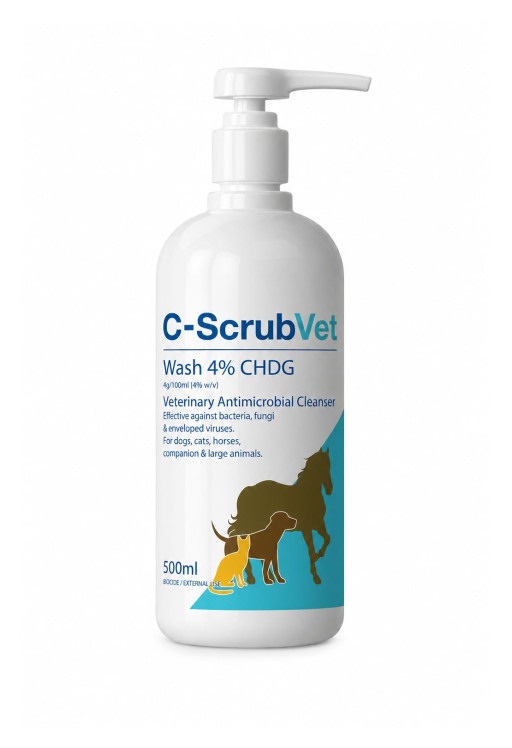
First orders received for the Company's veterinary antimicrobial line, which will be marketed under the brand name C-ScrubVet
Formulated for dogs, cats, horses, companion and large animals, and supplied in a 500ml pump-dispenser bottle
Sales have commenced in the United Kingdom, with additional European markets to follow from Q4 2026
Multichannel strategy initially focused on e-commerce, with planned expansion into pet store chains and veterinary clinics
Certified under European standards EN 1656 and EN 1657 for bactericidal and fungicidal activity in veterinary use
Manufactured in-house at Cana Laboratories' EU GMP-licensed, EMA-certified facility, consistent with the Company's vertically integrated model
Extends the C-Scrub franchise beyond human healthcare, addressing the $69 billion global animal health market
Expected to be one of several catalysts supporting the Company's previously issued 2029 guidance of $200.6 million in revenue, $44.2 million in adjusted EBITDA and $31 million in net income
No dilution to existing shareholders
Reduction in total outstanding warrant overhang
Simplifies capital structure
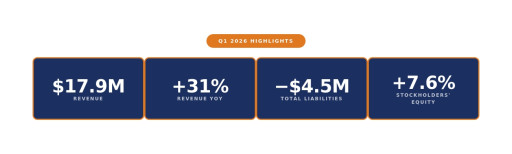
Record Q1 revenue of $17.9M, up 31% from $13.71 million in Q1 2025, reflecting strength across all core segments
Total liabilities decreased by $4.5M, or 9.6%, driven by a substantial reduction in convertible note and credit facility balances
Stockholders' equity increased by $1.4M, or 7.6%, with the liabilities-to-assets ratio improving by 370 basis points
Adjusted EBITDA near breakeven as increased revenue was offset by strategic investments to support global growth
Record momentum continues into Q2 2026 with U.S. expansion actively underway
Advisory Agreement Secured: To advance the Company's EIB-backed R&D financing program
€25 million potential financing opportunity: Up to 50% of the Company's €50 million planned R&D program
Institutional-grade capital: Potential long-term, attractively structured financing from the EU's premier development bank
R&D acceleration: Strengthens and expands the Company's development pipeline across its portfolio
Value creation catalyst: Landmark funding opportunity supporting long-term innovation and growth
2026 revenue forecast raised: Zacks increases 2026 revenue estimate to $103.2 million, up from $98.6 million in its prior January 2026 report
EPS outlook upgraded: Zacks now expects Cosmos Health to cross into positive EPS territory in 2026
$4.50 valuation reaffirmed: Updated report maintains valuation target, citing improving fundamentals and operational momentum
Long-term growth trajectory maintained: Zacks continues to project revenue of approximately $130.8 million in 2027
"Clear inflection point": Zacks highlights Cosmos Health's accelerating operational momentum and strategic evolution into a higher-margin healthcare platform with multiple growth vectors
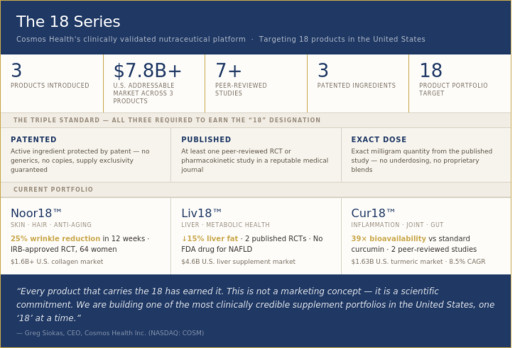
Science-first nutraceutical platform: Every "18" product must clear three criteria before reaching market - a patented ingredient, peer-reviewed clinical evidence, and the exact dose studied in clinical trials; a bar the vast majority of the supplement industry cannot meet
Three products introduced, $7.8 billion addressable market: Noor18™, Liv18™, and Cur18™ - targeting healthy aging & beauty, liver & metabolic support, and inflammation & mobility across three of the fastest-growing health categories in the U.S.
Institutional-grade scientific standard: Patented ingredients, published randomized controlled trials, exact clinical dosing - built to the standard of institutional science, not marketing
Compounding platform value, 18 clinically validated products targeted: Each new "18" product retroactively strengthens every existing one - the portfolio becomes more valuable with every addition
Clinically studied curcumin formulation demonstrating significantly enhanced absorption versus standard 95% curcuminoid extracts.
Derived predominantly from turmeric (~98.5%), maintaining a composition closer to the natural profile of the plant.
Utilizes a turmeric-derived ingredient described as self-affirmed GRAS and evaluated in published research showing up to 39× higher free curcumin bioavailability under study conditions.
Scaled contract manufacturing division, securing long-term agreements for over 12 million units
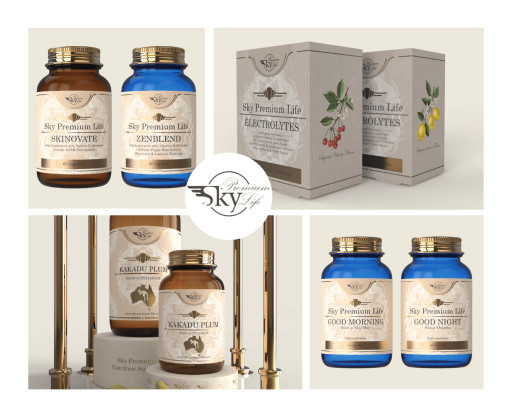
Expanded Sky Premium Life portfolio by 60 SKUs and accelerated global expansion, securing purchase orders for over 300,000 units across new markets
Advanced R&D pipeline, securing patented anticancer drugs, multiple AI-driven patent filings, and CCX0722 weight management product entering final development
Secured $300 million financing facility to launch digital asset treasury strategy
CEO Greg Siokas increased ownership by over 3.3 million shares, reinforcing deep insider conviction
Strong momentum continues into 2026 with record growth across all core segments and continued U.S. expansion underway
Powered by BergacynFF®, the only patented botanical blend clinically demonstrated to reduce liver fat accumulation and support healthy body weight in two independent randomized controlled trials.
Finalizing scale-up production phase
Engaging with Contract Research Organizations to complete the technical dossier
Clinical trials expected to complete in late 2025 or early 2026
Potential classification as a Class III medical device
Product launch expected in the first or second quarter of 2026
Further updates on progress to follow in the coming months